Gerardo Sanz-Maldonado
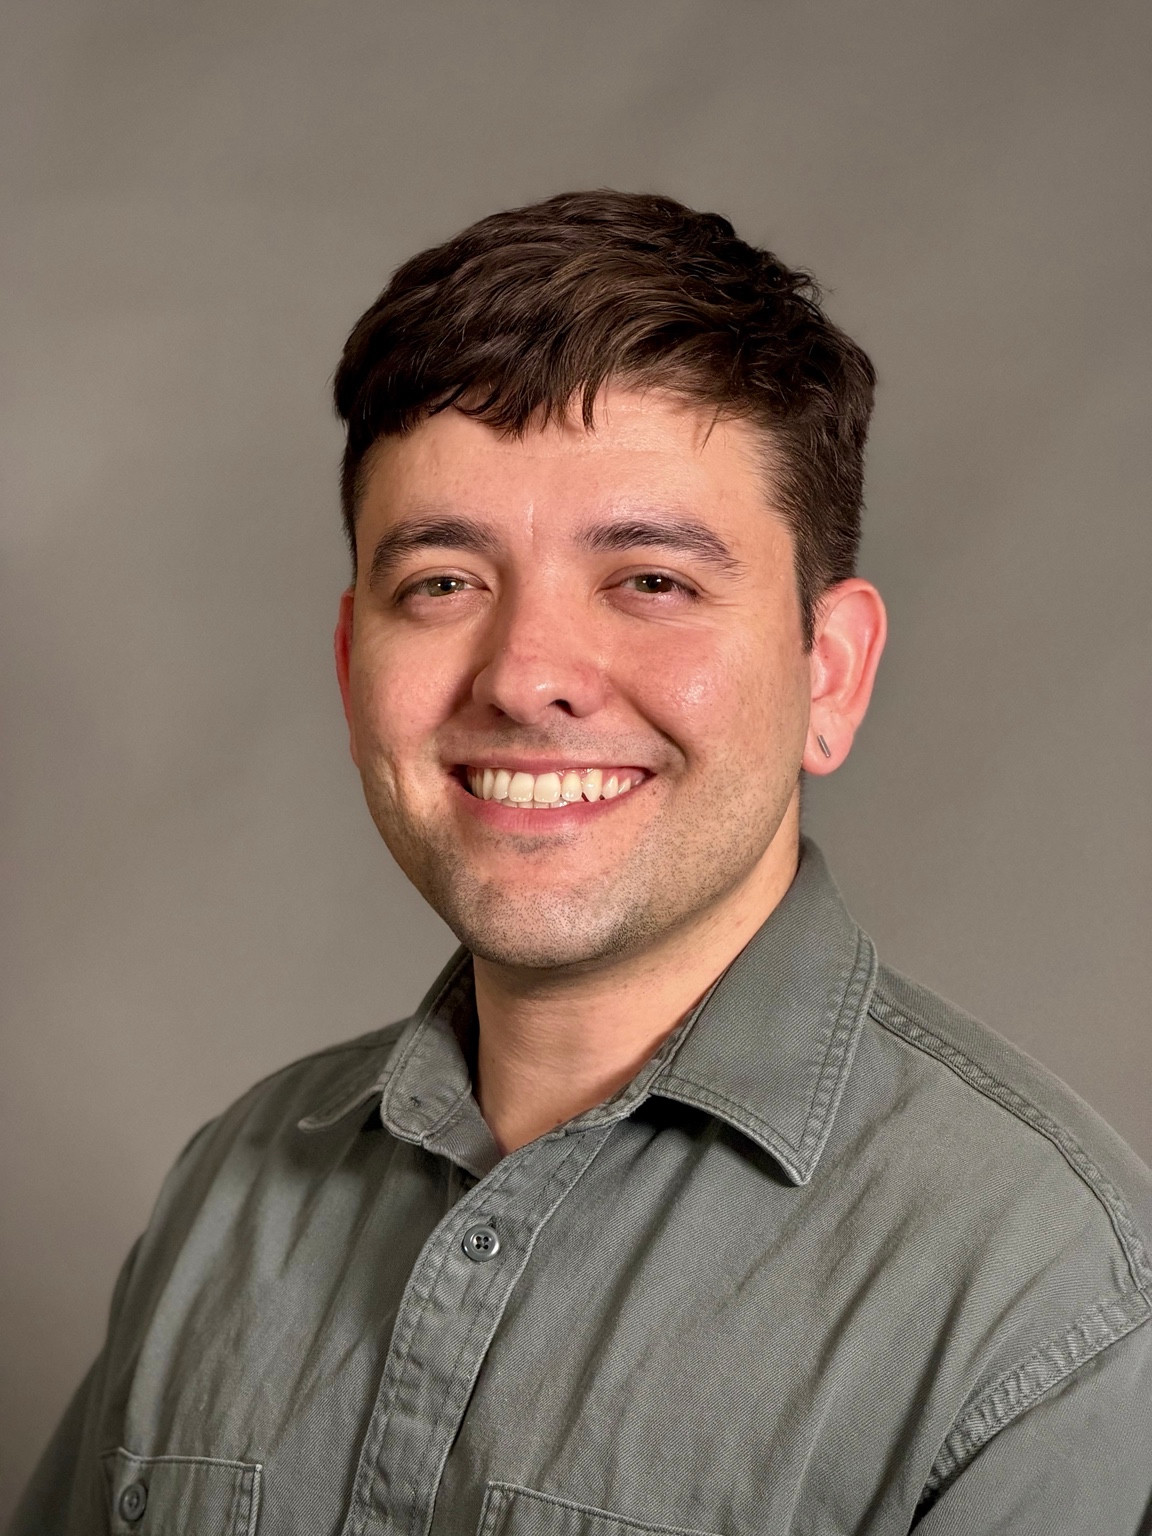
Portrait of Gerardo Sanz-Maldonado

Economics · University of Michigan

GerardoSanz-Maldonado

PhD Candidate in Economics
University of Michigan

I am on the job market for the 2026–2027 hiring season.

About Me

I am a public finance economist interested in digital markets and data privacy. My job market paper studies how France’s digital services tax affects web traffic to multinational digital platforms.

Before my PhD, I worked as a research assistant at the Federal Reserve Board (2017–2020). I earned my BA in Economics with Honors from Stanford University in 2017.

I have roots in San Juan, Puerto Rico, and Orlando, Florida.

Research

Job market paper & working papers

Job Market Paper

Taxing Multinational Digital Platforms: Evidence From France's Digital Services Tax

Latest draft (PDF)
Abstract

Digital service taxes are levies on the revenues of large multinational digital platforms attributed to local activity. This paper shows that their design generates behavioral incentives that can change the pattern of web traffic among liable sites and their non-liable counterparts. I study France's digital services tax using monthly traffic data for 55 website families owned by 20 liable corporate groups. I estimate an imprecise average traffic decline of 2.8 log percentage points among liable platforms. Further, the point estimate for nonliable sites exposed to digital advertising technologies is a decline of 8.2 log percentage points. Treatment effects among liable platforms are heterogeneous by business model: pure intermediation websites decline by 11.1 log percentage points, while advertising websites increase by 16.9 log percentage points. A model explains how reduced advertising intensity can attract users despite lower expenditure on services, while higher transaction fees on intermediation platforms discourage participation. The findings extend the assessment of digital taxation beyond price incidence.

Working Paper

Salary Disclosures and the Value of Salary Confidentiality

With Stephanie Karol

Reject and resubmit, Journal of Public Economics

Abstract

How much do taxpayers value salary confidentiality? We leverage administrative data to estimate a revealed preference-based sufficient statistic for the willingness to pay for earnings confidentiality. We exploit the fact that nonprofits are required to publicly disclose the names and salaries of certain employees whose taxable earnings exceed $100,000. We find that taxpayers who bunch below the threshold reduce their pre-tax income by up to $3,076 to avoid disclosure. Employees whose earnings have recently been disclosed are also more likely to separate from their employers. We argue that this is indicative of an employee demand for privacy.

Working Paper

External Validity in Empirical Public Finance: With an Application to Taxable Income Elasticities

With Meng Hsuan Hsieh and Joel Slemrod

R&R, under review at Journal of Public Economics

Abstract

We propose a three-step empirical Bayes framework, grounded in statistical decision theory, to combine evidence across countries. The framework models cross-country heterogeneity using structural determinants of tax systems and determines how much each country’s estimate should draw on external evidence. Countries with less precise local estimates receive more weight on cross-country evidence. Applying the framework to 27 OECD countries, we show how estimates of taxable income elasticities can incorporate evidence from other countries and outline how to predict behavioral responses in countries that have not adopted a given tax.

Working Paper

The Value of Tax Privacy: Evidence from an Online Survey of U.S. Adults

Abstract

I estimate the perceived private costs of tax return disclosure in the United States using hypothetical willingness-to-pay and willingness-to-accept exercises in an online survey of U.S. taxpayers. The median willingness to pay for tax privacy is $50, while the mean is $257, reflecting a highly skewed distribution. Approximately 30 percent of respondents report that the personal benefits of tax return disclosure outweigh its risks. Privacy valuations depend substantially on how they are elicited: median willingness to accept compensation for disclosure is four times median willingness to pay to prevent it. These findings inform the trade-off between the private costs of losing tax privacy and the social benefits of tax transparency.

Work in progress

Synthetic Data Methods for Linked Survey-Administrative Data

With Maggie Levenstein, Matthew Shapiro, Adam Shumway, and Evan Totty

[Draft coming soon]

References

James R. Hines Jr.

University of Michigan
Dissertation co-chair

Matthew D. Shapiro

University of Michigan
Dissertation co-chair

Joel Slemrod

University of Michigan
Dissertation committee member